Investors · Leasing & Financing
Leasing & Financing Resources
The financing and lease questions that shape a coastal investment — what lenders look at, how investor loans differ, and how a lease should protect the property.
Financing and leasing are where a good property plan either holds together or falls apart. This page is educational: it explains what to prepare and what to ask, not what you will be approved for.
Financing an investment property
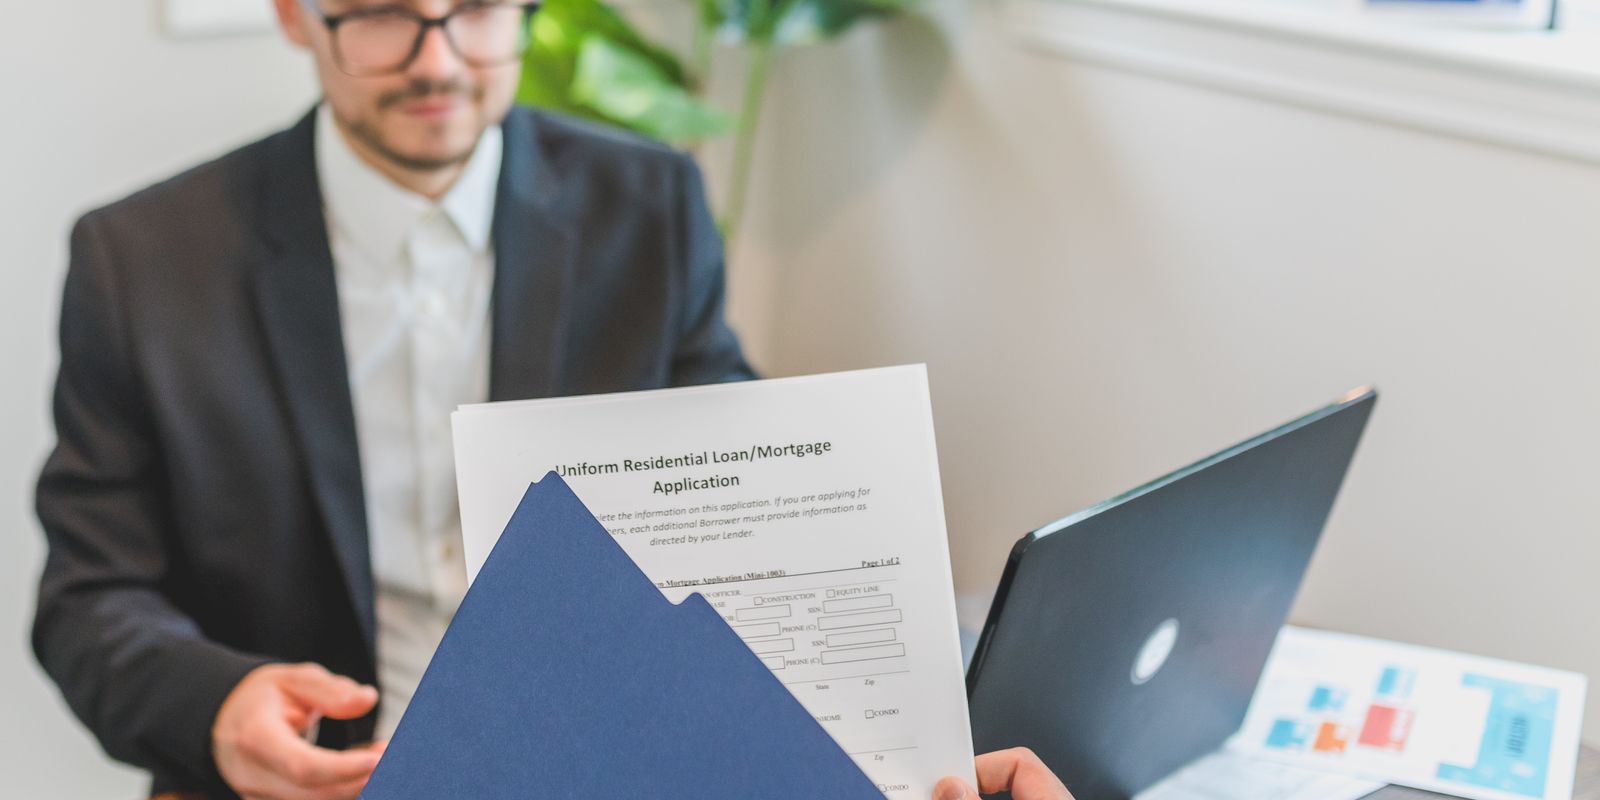
Investment property loans are underwritten differently from a primary residence. Expect a lender to look at the property's income potential, your reserves, your credit and your overall debt profile. Second-home and investor loans often carry different terms than owner-occupied loans.
- Primary residence, second home and investment property are priced and underwritten differently.
- Condo financing can depend on the building's project eligibility, occupancy and HOA status.
- Investor and portfolio lenders may look at the property's income in addition to your personal income.
- Documentation matters: tax returns, bank statements, rental history and a clear ownership structure.
What to prepare before you apply
- A realistic budget that includes dues, insurance, taxes and reserves.
- Recent income and asset documentation.
- A clear understanding of how the property will be used and rented.
- Insurance quotes — especially for coastal wind and flood exposure.
- Entity documents if you are buying through an LLC or other structure.
Leasing the property
A lease is the operating foundation of a long-term rental. It should set the term, rent, deposit, maintenance responsibilities and rules clearly, and comply with local and state requirements. Tenant screening and a documented move-in condition protect both sides.
- Use a written lease that fits South Carolina requirements.
- Screen tenants consistently and document the process.
- Clarify who handles repairs and how requests are submitted.
- Keep records of payments, notices and maintenance.
- Confirm the building or HOA does not restrict leasing terms.
Useful tools on this site
- Mortgage calculator for a rough payment estimate
- Affordability calculator for a budget starting point
- Partner lender resources for financing contacts
- Live listings to test scenarios against real properties
Common questions
Can I get financing for an oceanfront condo?
It depends on the building's eligibility and the lender's guidelines, as well as your own qualifications. Some buildings are easier to finance than others. Approval is never guaranteed.
Should I buy in an LLC?
The right structure depends on liability, tax and financing goals. Talk to a CPA and an attorney before you choose a structure, and confirm your lender allows it.
How much should I reserve after closing?
Enough to cover several months of carrying costs plus a realistic maintenance and vacancy cushion. The right number depends on the property and your risk tolerance.
Start with a realistic budget.
Use the calculators, then review the plan with a local advisor who knows coastal carrying costs.